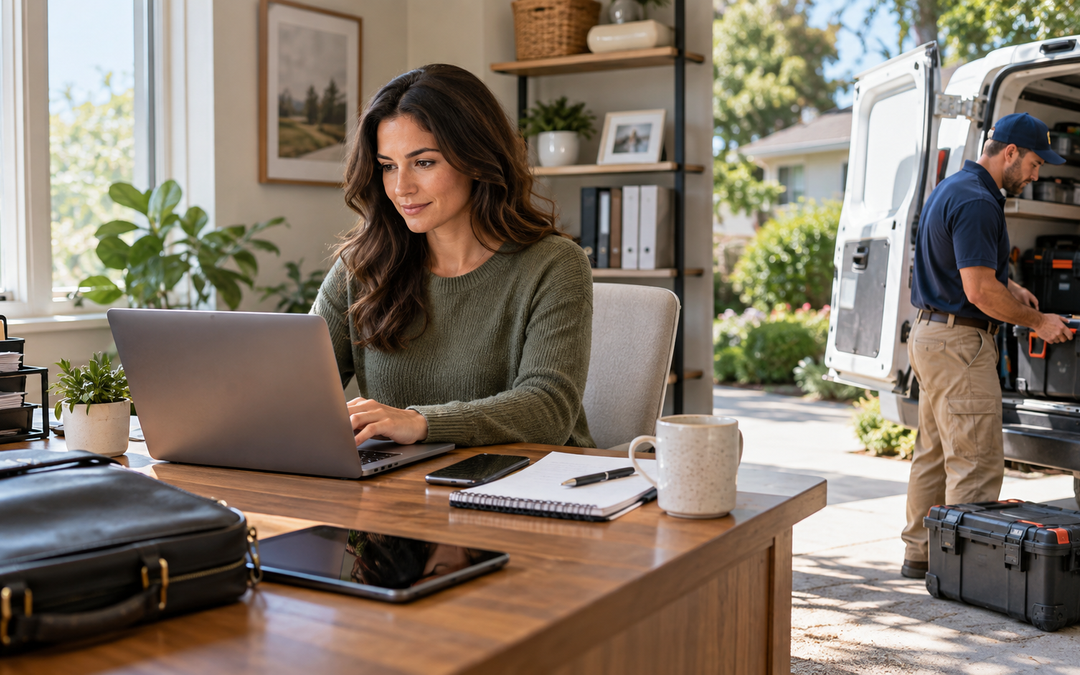
Remote and hybrid work have changed where business gets done. Your employees may take laptops home, carry equipment to client locations, travel with company property, or work from somewhere other than your main office.
That creates an important insurance question:
If company property is damaged, lost, or stolen while it’s away from your business location, is it still covered?
The answer is not necessarily.
Your commercial property policy is generally designed around the property and locations listed on your policy. The Google Business planning material for Karen Ray Insurance Agency specifically notes that standard commercial property coverage typically focuses on property at the primary business address. google my business plan
That means business owners shouldn’t automatically assume that “I have commercial property insurance” means “my property is covered everywhere.”
What Happens When Employees Take Business Property Off-Site?
Consider a medical office that gives an employee a company laptop to work from home. Or an artisan contractor who regularly takes thousands of dollars’ worth of tools from the shop to job sites.
Those assets aren’t sitting at the location shown on the commercial property policy.
If the laptop is stolen from the employee’s home or the contractor’s equipment is damaged away from the shop, the business could discover that its standard property coverage is limited—or doesn’t respond the way the owner expected.
That’s why I want business owners to think about where their property actually goes, not just where their business is located.
What Coverage Can Protect Property Away From Your Business?
Depending on the business and policy, there are a couple of ways we may be able to address this exposure.
Inland Marine Coverage
Don’t let the name confuse you—it isn’t just insurance for things on boats.
Inland marine coverage can be used to protect certain business property that moves from place to place. This can be particularly important for businesses with tools, equipment, computers, or other valuable property that routinely leaves the primary business location.
Our commercial insurance planning guide specifically identifies inland marine as a solution for tools, gear, and equipment that travels. google my business plan
Off-Premises Property Coverage
Some commercial policies may also offer endorsements or extensions for business property temporarily located away from the insured premises. For example, an endorsement may extend protection to company-owned equipment being used in an employee’s home office. google my business plan
The important part is checking the actual policy. Coverage limits, deductibles, covered causes of loss, geographic restrictions, and exclusions can vary significantly. GET A QUOTE
Don’t Forget About Laptops and Electronics
One of the easiest exposures to overlook is technology.
Imagine you have five employees working remotely, each with a $2,000 laptop, monitors, docking stations, and other company-owned electronics. You could quickly have $15,000 or more of business property scattered across several locations.
Now ask yourself:
Does my insurance company know that’s how we’re operating?
That’s a much better question to answer before something is stolen or damaged.
There is another issue here, too: insuring the physical laptop doesn’t necessarily protect the information stored on it. Property coverage and cyber liability address different risks. Your commercial insurance program may need to consider both physical equipment and your exposure to data breaches, ransomware, or compromised customer information.
What About Employees’ Personal Property?
There is an important distinction between company-owned equipment and an employee’s personally owned equipment.
If an employee uses their own laptop, monitor, phone, furniture, or other property for work, don’t automatically assume your commercial property policy insures those items.
Ownership matters.
That’s another reason I recommend documenting which equipment belongs to the business, who has it, and where it is normally used.
A Simple Business Property Check
If you have employees working remotely or your business regularly operates away from its primary location, take a quick inventory. Ask:
- What company property regularly leaves our business?
- Approximately how much would it cost to replace it?
- Do employees keep company equipment at home overnight?
- Do we have tools or equipment that move between job sites?
- Do employees travel with laptops or other electronics?
- Does our current policy provide off-premises coverage, and what is the limit?
You may find that your current policy already provides some protection. You may also discover a gap that can be addressed with an endorsement or separate coverage.
The Bottom Line
Commercial property insurance can protect your business assets, but don’t assume your coverage automatically follows your property everywhere it goes.
If employees work remotely, travel, visit customers, or take company equipment home, your insurance should reflect the way your business actually operates.
At Karen Ray Insurance Agency, we help Texas business owners look beyond the policy name and understand what their insurance is actually designed to protect. Commercial coverage can include property, general liability, workers’ compensation, and other protections depending on the business and its risks. CONTACT US